Blainville (Nord)
What Is the Monthly Payment on a $200K Mortgage?
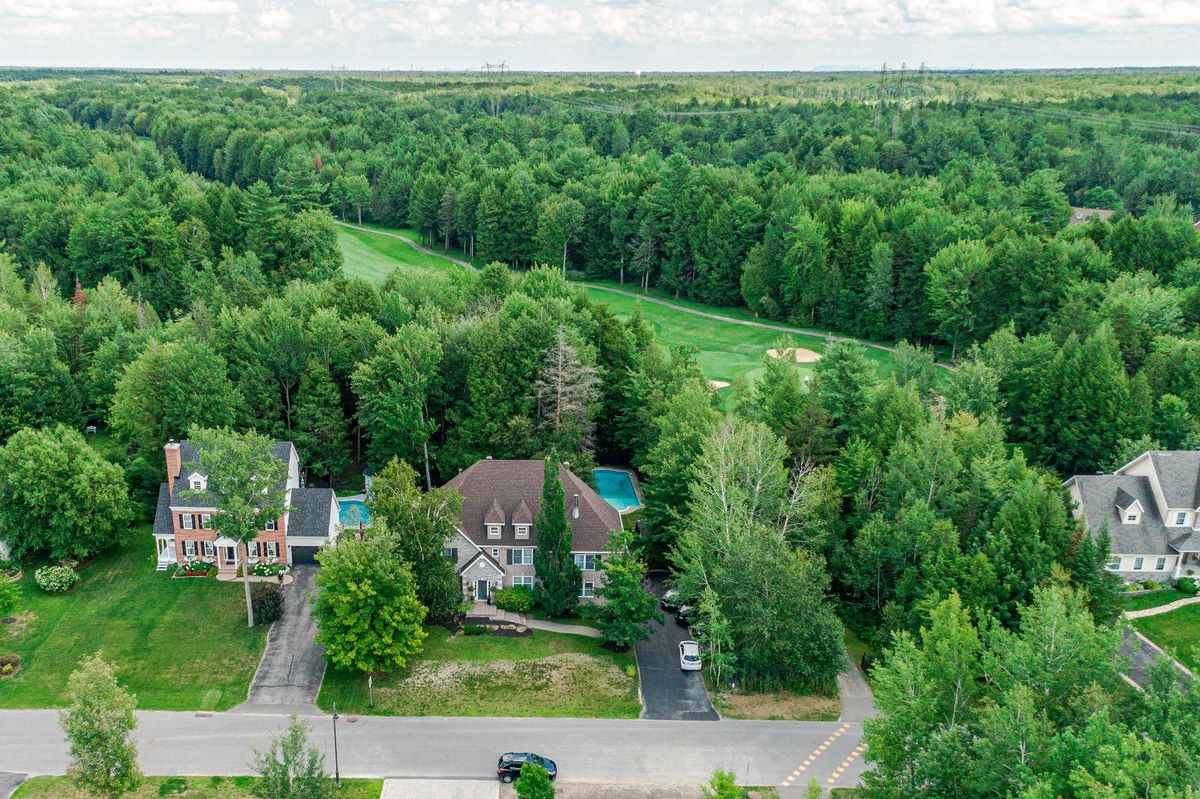
Nestled within the serene Blainvillier sector, alongside the lush greens of the Golf course, stands an exquisite abode deserving of utmost admiration. This distinguished cottage boasts five expansive bedrooms, each meticulously crafted as individual sanctuaries, offering every family member their own private retreat complete with a full bathroom and a spacious walk-in closet. Step outside and be captivated by the sprawling wooded grounds, providing both ample space and privacy, along with parking accommodations for up to seven vehicles and a stunning in-ground saltwater pool.
- Lot area16,146 SF
- Number of rooms27
- Year built1999
5 Bedrooms5 Bathrooms1 Washrooms2 Double width or moreInground PoolWood fireplace
Building details and property interior
- Size
- 60'6" X 40'4" Irregular
- Year built
- 1999
- Foundation
- Poured concrete
- Siding
- Aggregate, Brick
- Roofing
- Asphalt shingles
- Garage
- Attached, Heated, Double width or more
- Bathroom
- Ensuite bathroom, Separate shower
- Basement
- 6 feet and more, Finished basement
Lot and exterior features
- Lot size
- 98'5" X 164' Irregular
- Lot area
- 16,145.87 SF
- Lot
- Fenced, Wooded, Landscaped
- Topography
- Flat
- View
- Panoramic
- Driveway
- Asphalt
- Parking (total)
- Driveway : 8, Garage : 2
- Pool
- Heated, Inground
- Proximity
- Highway, CEGEP, Daycare centre, Golf, Hospital, Park, Bicycle path, Elementary school, Alpine skiing, High school, Cross-country skiing, CARAC.PROX.SMOT, CARAC.PROX.SVTT, Commuter train, Public transportation, University
Characteristics
- Heating System
- Forced air
- Heating Energy
- Dual energy, Electricity, Heating oil
- Fireplace-Stove
- Wood fireplace, Wood stove
- Equipment/Services
- Central vacuum cleaner system installation, CARAC.EQUI.BALC, CARAC.EQUI.COUR, Central heat pump
- Water Supply
- Municipality
- Sewage System
- Disposal field, Septic tank
Included & Excluded
- Included
- Cooktop, built-in oven, dishwasher, all blinds, pool heat pump (2020), central vacuum, small generator.
- Excluded
- Curtains, all appliances, pendant light in basement, TV stands, all owners personal effects.
The monthly payment on a $200,000 mortgage typically ranges from $1,200 to $1,700, depending on your interest rate, loan term, down payment, and whether you include property taxes, homeowners insurance, and private mortgage insurance (PMI). For example, a 30-year fixed-rate mortgage at 6% interest with a 20% down payment results in a principal and interest payment of about $1,199 per month, while a 15-year loan at the same rate would be about $1,400 per month. These figures exclude taxes and insurance, which can add several hundred dollars more.
Your exact payment will vary based on your credit score, loan type, and local costs. This guide breaks down the key factors, provides sample calculations, and explains how to estimate your total monthly obligation.
How the Loan Term Affects Your Payment
The loan term is the number of years you have to repay the mortgage. The most common terms are 30 years and 15 years. A longer term spreads payments over more months, lowering your monthly bill but increasing total interest paid. A shorter term raises monthly payments but saves significantly on interest over the life of the loan.
For a $200,000 loan at a 6% fixed interest rate, the principal and interest payment is approximately $1,199 per month on a 30-year term and $1,688 per month on a 15-year term, according to Credible and standard mortgage calculations. At a 7% rate, the 30-year payment rises to about $1,331 per month, as noted by Finder. These figures assume you borrow the full $200,000. If you make a 20% down payment on a $200,000 home, your loan amount would be $160,000, and your payments would be lower: about $959 per month for 30 years and $1,350 for 15 years at 6%.
Choosing between a 30-year and 15-year mortgage depends on your budget and long-term goals. A 30-year loan offers lower monthly costs, which can free up cash for other expenses or investments. A 15-year loan builds equity faster and can save tens of thousands in interest, but requires a higher monthly payment.
The Role of Interest Rates
Interest rates are the single biggest lever on your monthly payment. Even a small difference in rate can change your payment by a meaningful amount. For a $200,000 loan, a 1% rate increase can add over $100 to your monthly payment on a 30-year term.
As of 2026, rates for a 30-year fixed mortgage are around 6% to 7%. At 6%, the principal and interest payment on a $200,000 loan is about $1,199 per month, according to Credible. At 7%, it rises to about $1,331 per month, as noted by Finder. For a 15-year term at 7%, the payment would be approximately $1,798 per month.
Your credit score heavily influences the rate you receive. Borrowers with higher credit scores typically qualify for lower rates, which can save thousands over the life of the loan. Shopping around with multiple lenders or working with a mortgage broker can help you find a competitive rate.
Down Payment and Private Mortgage Insurance (PMI)
Your down payment directly affects your loan amount and whether you must pay PMI. Most conventional loans require at least 3% down, but putting down 20% or more allows you to avoid PMI. PMI protects the lender if you default and typically costs between 0.3% and 1.5% of the original loan amount annually, according to reAlpha.
On a $200,000 home, a 20% down payment is $40,000, leaving a loan amount of $160,000. If you put down only 5% ($10,000), your loan amount is $190,000, and you'll pay PMI until your loan-to-value ratio reaches 80%. PMI can add $50 to $250 per month, depending on your credit and down payment.
A larger down payment also reduces your monthly principal and interest payment because you're borrowing less. For example, borrowing $160,000 at 6% for 30 years results in a payment of about $959 per month, while borrowing $190,000 at the same rate results in about $1,139 per month.
Property Taxes, Homeowners Insurance, and HOA Fees
Your monthly mortgage payment often includes more than principal and interest. If you have an escrow account, your lender collects money each month to pay property taxes and homeowners insurance on your behalf. These costs vary by location and can significantly increase your total payment.
Property taxes in the U.S. average about 1.1% of a home's value annually, but can range from under 1% to over 2% depending on the state and county. On a $200,000 home, that's roughly $2,200 per year, or about $183 per month. Homeowners insurance costs vary based on factors like location, coverage amount, and property condition, but a typical policy might cost $100 to $200 per month.
If your home is in a community with a homeowners association (HOA), you'll also pay monthly or annual HOA fees. These fees cover maintenance of common areas and amenities and can range from $50 to several hundred dollars per month. When budgeting, include all these costs to get a realistic picture of your total monthly housing expense.
Sample Monthly Payments for a $200K Mortgage
The table below shows estimated principal and interest payments for a $200,000 loan at different interest rates and terms. These figures do not include taxes, insurance, or PMI.
| Interest Rate | 30-Year Term | 15-Year Term |
|---|---|---|
| 6.0% | $1,199 | $1,688 |
| 6.5% | $1,264 | $1,742 |
| 7.0% | $1,331 | $1,798 |
These calculations are based on the standard mortgage formula and align with figures from Calculator.net and other sources. To get a personalized estimate, use an online mortgage calculator that includes taxes, insurance, and PMI.
How to Estimate Your Total Monthly Payment
To estimate your total monthly payment, start with the principal and interest amount based on your loan amount, term, and interest rate. Then add monthly property taxes (annual tax divided by 12), homeowners insurance (annual premium divided by 12), and PMI if your down payment is less than 20%. If applicable, add HOA fees.
For example, suppose you borrow $180,000 (after a 10% down payment on a $200,000 home) at 6.5% for 30 years. Your principal and interest payment would be about $1,138. Add $183 for property taxes, $150 for insurance, and $100 for PMI, and your total monthly payment would be approximately $1,571. This is within the typical range cited by reAlpha.
Keep in mind that your actual payment may differ based on your specific circumstances. Lenders also consider your debt-to-income ratio, credit history, and other factors when approving a loan. For a more accurate figure, consult with a mortgage professional or use a detailed calculator like the one at Calculator.net.
Frequently Asked Questions
What salary do you need for a $200,000 mortgage?
Lenders typically require your total monthly debt payments, including your mortgage, to be no more than 36% to 43% of your gross monthly income. Assuming a total monthly payment of $1,500 and no other debts, you would need a gross monthly income of about $3,500 to $4,200, or $42,000 to $50,400 per year. However, this varies by lender and your other financial obligations.
Can I afford a $200K house on $50K a year?
With a $50,000 annual income, your gross monthly income is about $4,167. If your total monthly payment (including taxes and insurance) is $1,500, that's 36% of your income, which is at the upper limit of what many lenders allow. You may qualify, but you should carefully consider your other expenses and savings goals.
How to pay off a $200,000 mortgage in 5 years?
Paying off a $200,000 mortgage in 5 years requires aggressive extra payments. At a 6% interest rate, the monthly payment for a 5-year term would be about $3,867. This is not feasible for most borrowers, but you can accelerate payoff by making biweekly payments, adding extra principal each month, or refinancing to a shorter term when rates are favorable.
Recommended Resources: